1. Why did my credit score drop even though I paid all my bills on time?
Many consumers are shocked to discover that paying bills on time is only one factor used in credit scoring. High utilization, excessive inquiries, account closures, reporting errors, debt collection activity, and changes to your credit mix can all impact your score—even when you've never missed a payment. That's why understanding how credit actually works is often more important than simply paying your bills.
2. Is it true that some debts may be inaccurate, uncollectible, unenforceable, or eligible for cancelation and forgiveness?
Yes. Not every debt is automatically valid or collectible. Consumer protection laws provide rights that allow individuals to request verification, challenge inaccuracies, dispute improper reporting, investigate ownership of debts, and explore available hardship, settlement, discharge, or forgiveness programs. Understanding the nature of a debt is often the first step toward determining the options available.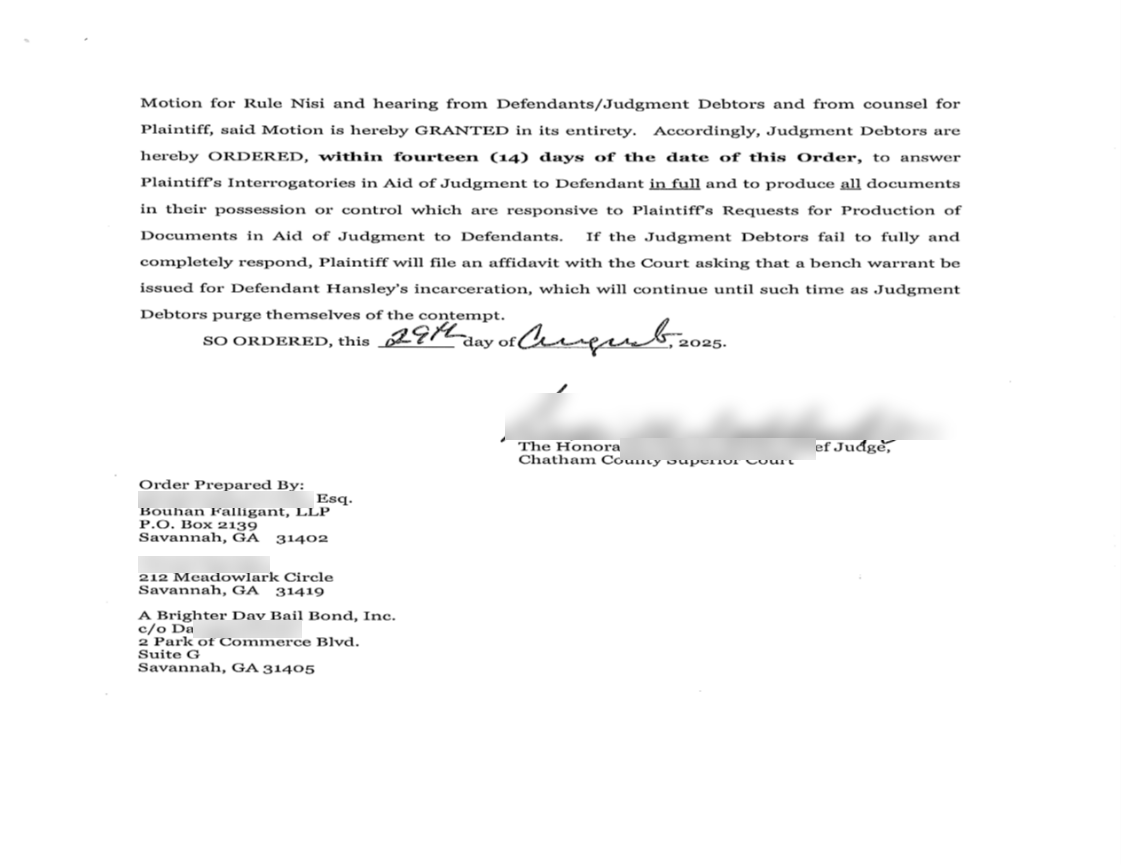
3. Could your credit profile be worth more than your paycheck?
For many successful entrepreneurs, investors, and business owners, access to credit has helped create opportunities that far exceed earned income alone. A strong credit profile can influence access to financing, business capital, real estate opportunities, and other financial resources. The question isn't whether credit matters—it's whether you're using it strategically enough to unlock its full potential. With your 720 or higher credit score you can access up to $250,000 unsecured. With your 800 credit score you can access up to $1,000,000.
4. what is zombie debt
Zombie debt is an old, defaulted bad debt that resurfaces after being charged – off forgotten, paid off, or discharged. Debt collectors buy these accounts for pennies on the dollar and try to secure payments, even if the debt is past the legal statute of limitations or has already been forgiven. They are counting on your fear and ignorance to help them get money for a debt that you don’t owe.
- Common Types of Zombie Debt A debt collector may contact you about several forms of resurfaced debt:
- Time-Barred Debt: Debt that is too old for a collector to legally sue you over (typically 3 to 6 years, depending on state law and the type of debt).
- Discharged or Settled Debt: Obligations that were previously wiped out in bankruptcy or settled for less than the total amount.
- Zombie Mortgages: Old second mortgages or home equity loans from before 2008 that sat dormant and are suddenly revived by collection firms demanding decades of back interest.
- Fraud or Identity Theft: Debts mistakenly linked to your name or opened by a thief.
- Defaulted Student Loans now that the us treasury has been assigned all defaulted student loans they have the ability to resolve these debts with extreme prejudice
- Common Types of Zombie Debt A debt collector may contact you about several forms of resurfaced debt:
The Risks: Ususally these debts balloon in cost and will eventually result in debt litigation if not properly handled. The biggest danger of zombie debt is that making even a single partial payment can legally "restart the clock" on the statute of limitations, giving the collector the right to sue you and collect a debt that was dead. Thus making the debt live again.
How to Protect Yourself: If a debt collector contacts you about an old debt, be very careful about what you say or agree to. Never make a payment or admit you owe the debt without first investigating. Request a debt validation letter: Under the federal Fair Debt Collection Practices Act (FDCPA), you can request written proof of the debt, including the original creditor and the amount owed. Send a dispute letter: If the debt is time-barred, you can send the collector a certified letter requesting they stop contacting you. Report abuses: If collectors use illegal threats, harassment, or abusive language, submit a complaint to the Consumer Financial Protection Bureau (CFPB). this video offers helpful guidance:
https://www.youtube.com/watch?v=2U9kSz1pFhs
STOP ALL ZOMBIE DEBT NOW
5. Is there such thing as Debtors Prison?
Yes you can now be arrested for failing to comply with debt litigation. Please don’t ignore debt collections any more. Call us. Here is an example of a client that was almost arrested for a bad debt: